Ever wonder what exactly a cash balance plan entails? For your clients who own small businesses, opening a cash balance retirement plan might be a vehicle for delivering significant tax savings (and looking like a hero while doing it).
What is a cash balance plan? As you know, there are two broad categories of tax-qualified, employer-sponsored retirement plans: (1) defined contribution plans, which provide benefits determined by employer and employee contributions to the plan, and (2) defined benefit plans, which provide benefits determined pursuant to a benefit formula set forth in the plan document.
A cash balance plan is a type of defined benefit plan, albeit one that has a hybrid of other retirement plan features. Unlike a traditional defined benefit plan, for example, the plan formula in a cash balance plan describes a participant’s benefit in terms of a current account balance (typically one equal to pay credits, interest credits, and earnings thereon).
So, what about the tax savings piece? Cash balance plans have a higher contribution limit than defined contribution plans and can provide small business owners with another “bucket” for tax savings. Cash balance plans are funded entirely by employer contributions—and, as these are tax-deductible to the sponsoring employer, they can provide material tax savings beginning the first year of the plan.
Happily, cash balance plans can be maintained alongside a 401(k) or profit-sharing plan. Each is generally subject to different maximum limits under the Tax Code so the tax savings here are cumulative.
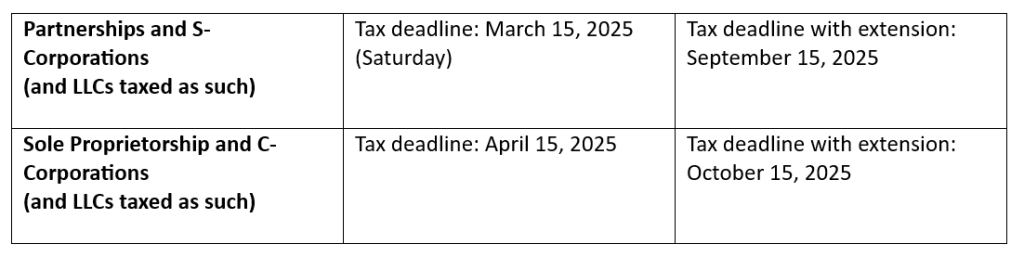
What’s the deadline for establishing a cash balance plan? Thanks to the SECURE Act, small business owners now have until their corporate tax filing deadline (including extensions) for the plan’s initial year. This means your clients generally have until the following deadlines to set up (and fund!) a cash balance plan for 2024:
Is there a catch? It is important to remember that setting up a cash balance plan is like setting up any other retirement plan—there are various statutory and regulatory requirements that apply to the plan. Cash balance plans in particular, come with unique administrative complexities. This should not be treated as a temporary holding space and should instead be considered carefully with your trusted TBC advisor to ensure your small business client is ready for the duties and administrative complexity that come with maintaining a cash balance plan.
Sounds great, what’s next? Now is a great time to reach out to your trusted TBC advisor for more information about whether a cash balance plan would be a good fit for your clients, or to just learn more about cash balance plans in general.
Copyright 2025 Poyner Spruill